We learn so much at school, but how much do we really learn about managing money?
For many Australians, understanding money comes through trial and error.
We start our first job, receive our first payslip, open a bank account and eventually begin making bigger financial decisions. Yet many of us reach adulthood without fully understanding how to budget, save, use credit or manage debt.
And while these things might seem straightforward once you’ve learned them, they’re not always obvious when you’re starting out.
The good news? Financial literacy is something we can all learn, regardless of our age or financial situation.
What is financial literacy?
Financial literacy is simply having the knowledge and confidence to make informed decisions about your money.
It’s understanding everyday things like:
- How to create and manage a budget.
- The difference between saving and spending.
- How interest rates work.
- What a credit score is and why it matters.
- How loans, credit cards and debt work.
- How to plan for future financial goals.
You don’t need to become a financial expert. You just need to understand enough to make decisions that work for you.
And importantly, you don’t need to know everything before you start.
Five money skills every young adult should learn
1. Understanding your first payslip
Getting your first job is exciting, especially when that first pay lands in your account!
But understanding your payslip is just as important as earning the money.
Knowing the difference between gross and net income, how tax works and what superannuation means can help you understand where your money is going.
These are things we often learn only after we start working.
2. Learning how to budget without giving up everything you enjoy
Budgeting sometimes gets a bad reputation.
People often think it means cutting out takeaway coffees, weekends with friends or anything fun.
But a budget isn’t about restricting everything you enjoy. It’s about understanding how much money you have coming in, what needs to go out and what you can comfortably spend.
Even a simple budget can help you build better money habits.
3. Building a savings habit early
You don’t need hundreds of dollars each week to start saving.
Sometimes it’s as simple as putting aside $5, $10 or $20 whenever you get paid.
The amount isn’t always the most important part. It’s about building the habit of saving consistently.
Over time, those small amounts can help you work towards bigger goals, whether that’s your first car, moving out of home, travelling or eventually buying a property.
4. Understanding credit before using it
Credit cards, personal loans and buy now, pay later services can make purchasing things easier.
But borrowing money comes with responsibilities.
Understanding interest, repayments, fees and how your borrowing behaviour can affect your credit history is an important part of managing money.
Learning these things before taking on debt can help you make more informed decisions.
5. Planning for life’s bigger expenses
Life has a way of becoming expensive!
Your first car, moving out of home, unexpected bills and eventually purchasing property can all come with costs you might not have considered.
Learning to plan ahead, research expenses and build a financial buffer can help you feel more prepared when those moments arrive.
And that’s really what financial literacy is about — having the tools to navigate life’s financial decisions with greater confidence.
Why I wrote Life Costs Money – Now What?
After more than 20 years working in finance, I’ve had countless conversations with people who simply weren’t taught some of the basics about money.
Not because they weren’t capable of understanding them, but because nobody had explained them in a way that made sense.
It’s also one of the reasons I created Your Finance Lounge.
I wanted to build a place where people could ask everyday money questions, learn at their own pace and feel comfortable starting from the beginning.
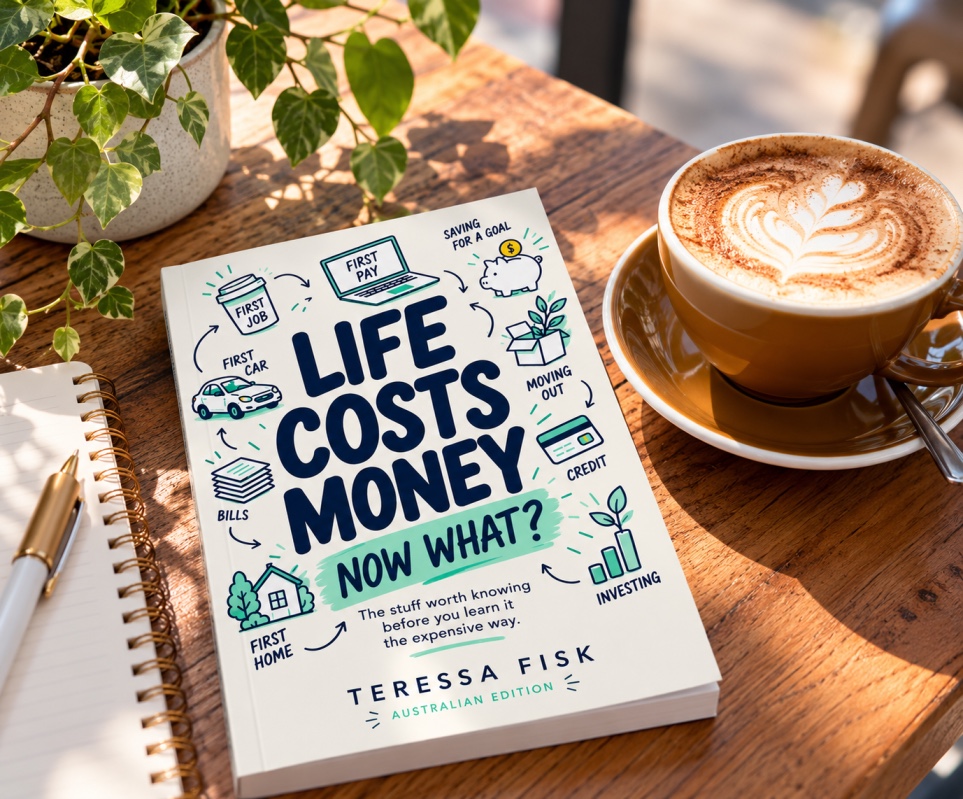
That same idea inspired my new book, Life Costs Money – Now What?
Written primarily for teenagers and young adults aged around 14 and over, the book is a practical introduction to managing money and preparing for the financial decisions that come with growing up.
From earning your first pay and building savings to understanding credit, buying your first car and preparing to move out of home, it covers real-life money topics in a straightforward, approachable way.
I’ve also included practical activities, checklists and worksheets to help readers put what they’re learning into action.
Because learning about money shouldn’t feel complicated or intimidating.
Discover Life Costs Money – Now What?
It’s never too early — or too late — to learn about money
While financial education is particularly valuable for young people, these lessons aren’t just for teenagers.
Many adults are still learning how to budget, understand borrowing, manage debt or improve their financial habits.
And that’s completely okay.
Financial literacy isn’t about getting everything right. It’s about continuing to learn, asking questions and making small improvements along the way.
Whether you’re starting your first job, saving for your first home or simply wanting to feel more confident with your finances, every little bit of knowledge helps.
Start where you are, learn what you can and build from there.
That’s what Your Finance Lounge is all about.
Learn. Grow. Build a brighter money future.
General information only. This article is for educational purposes and does not take into account your personal financial circumstances, objectives or needs. Consider seeking professional advice where appropriate.